BUSINESS
The Euro Hits a 17-Month Low After France’s Budget Scare
The euro fell to a 17-month low after weak U.S. jobs, as French fiscal stress revived 2011-style bond spreads.

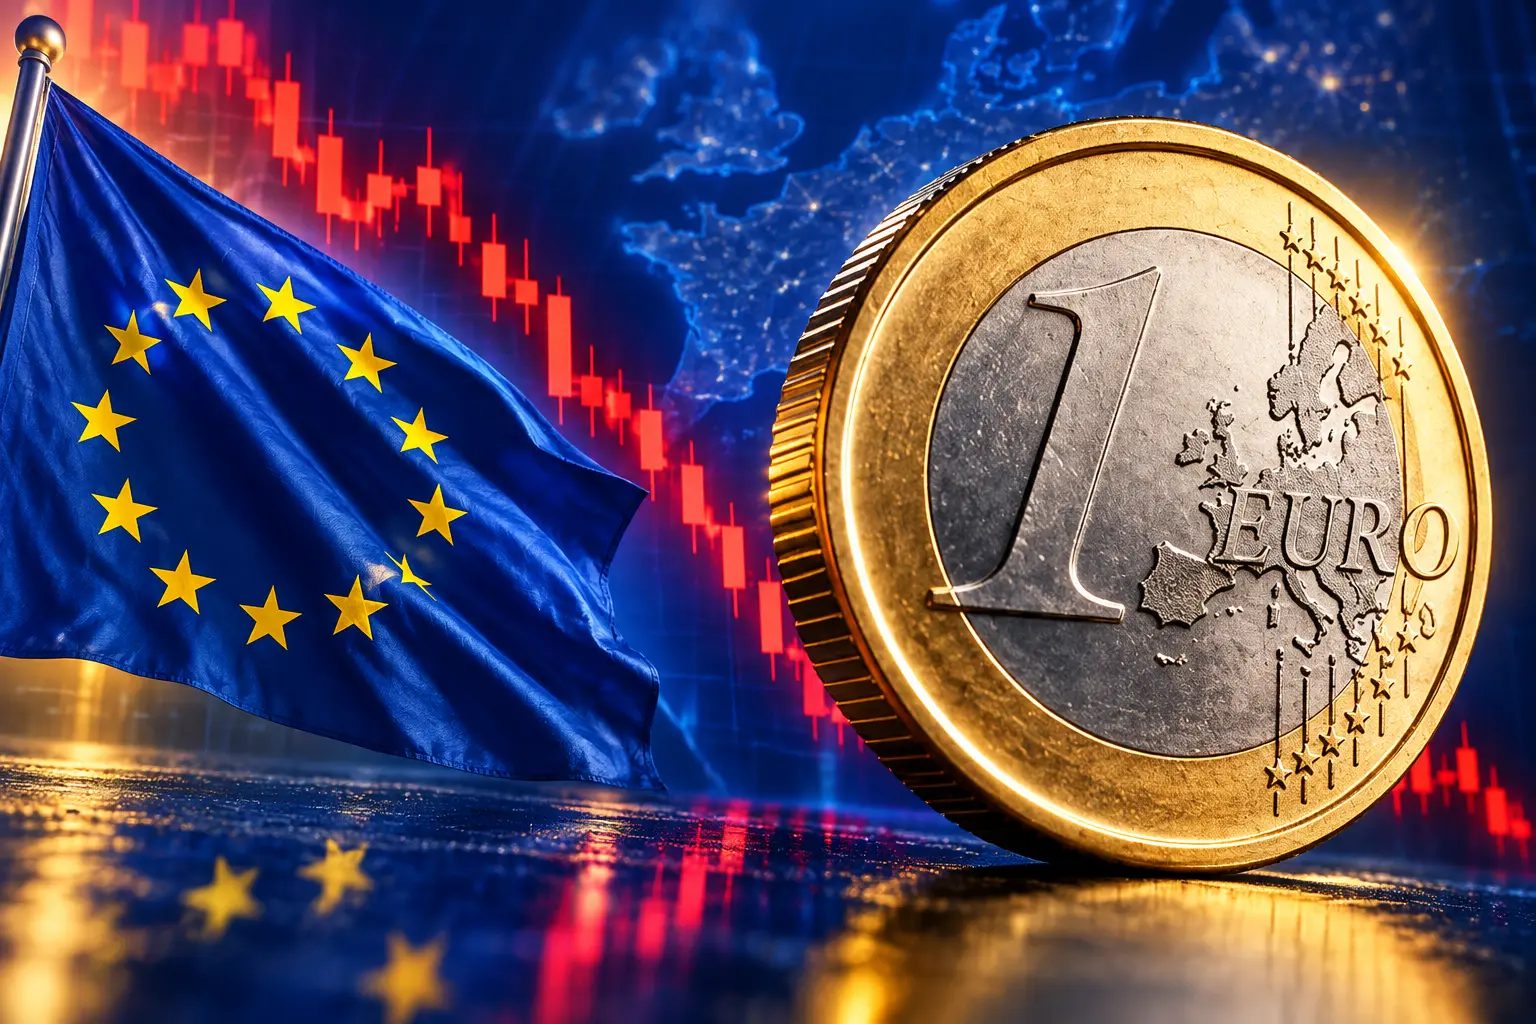
The euro fell to $1.1161 on Monday, a 17-month low, even after U.S. payrolls rose just 29,000 in September. The single currency was last at $1.1178, down 0.67 percent, after four straight weekly declines.
French borrowing costs and a minority government in Paris did the damage the U.S. jobs miss was supposed to do to the dollar. Global bond yields had already jumped last week, and France’s 10-year yield premium over Germany reached 154 basis points on Friday, the widest since 2011.
Friday’s Jobs Print Did Not Rescue the Euro
The U.S. Bureau of Labor Statistics said nonfarm payrolls rose by 29,000 in September, and the unemployment rate stood at 4.2 percent. Forecasters had clustered near 90,000, so the print landed well below the range markets had used to keep an October Federal Reserve hike in play.
July was revised from a 21,000 gain to a 10,000 loss, and August was cut from 162,000 to 133,000. Combined, those two months are 60,000 jobs lighter than first reported. Average hourly earnings rose 5 cents, or 0.1 percent, to $37.81, and are up 3.0 percent over 12 months.
SEPTEMBER U.S. JOBS IN BRIEF
- Payrolls: Employers added 29,000 jobs, against a 90,000-style consensus.
- Jobless rate: Unemployment held in a 4.1 to 4.3 percent band that has lasted since March, printing 4.2 percent.
- Revisions: July and August together came in 60,000 lower than first reported.
- Pay: Average hourly earnings rose 0.1 percent on the month and 3.0 percent on the year.
Fed funds futures cut the chance of a move at the Oct. 27-28 meeting, then nudged it back only as far as the low 20s. Mansoor Mohi-uddin, chief macro strategist at Bank of Singapore, said the labor market is not overheating even though inflation has stayed above the Fed’s 2 percent target since the pandemic, and he expects rates to be left unchanged at that October meeting. The U.S. 10-year yield was at 5.262 percent on Monday, below a 24-year high printed last week. That is the part that should have taken heat off the dollar. It did not save the euro.
France Pays a 2011-Style Bond Premium
France’s 10-year yield touched 4.96 percent on Thursday, Oct. 1, the highest since July 2002, after investors gave a cool reception to the 2027 budget. French bond futures dipped 0.13 percent on Monday, still hugging the lows of the past few weeks. Jim Reid, a Deutsche Bank strategist, flagged a 13.9 basis-point daily jump in the Franco-German 10-year gap as the biggest since March 2020.
On Friday the extra yield investors demanded to hold 10-year French debt over German bunds reached 154 basis points, a gap last seen in 2011, when Greece’s fiscal problems forced the European Central Bank to step in. Early in 2026 that French premium was still around 55 basis points. Bunds caught a safety bid as OATs sold off, which is how the spread can blow out even when the French yield ticks a little lower from its Thursday peak.
The speed is the new piece. Jens Nordvig, president and co-founder of Vanda, compared the current burst with the 2011 sovereign-bank scare and found 67 basis points of widening in less than a month, against 104 basis points over 106 days back then. France is also a much larger borrower than Greece was, and its debt is near 120 percent of GDP against something closer to 80 percent in 2009.
Euro-Crisis II?
French bond spreads have widened more than in the Greek debt crisis of 2010 and also more than during the period of Spanish denomination risk concern in 2012.
Even compared to the most intense period of the Euro-crisis (the sovereign debt / bank nexus of 2011)… pic.twitter.com/izuMy4FNdp
— Jens Nordvig (@jnordvig) October 4, 2026
In 2011 France was mostly a bystander while German yields fell faster than French ones. This time French yields are rising outright, and France is at the front of the euro-area spread move. Sumitomo Mitsui DS Asset Management sold its entire French government bond holdings and shifted into bunds and Japanese debt, a reminder that a long-standing foreign bid can leave.
MONDAY’S CURRENCY AND YIELD BOARD
| Market | Level | Move |
|---|---|---|
| Euro vs dollar (last) | $1.1178 | down 0.67% |
| Euro vs dollar (low) | $1.1161 | weakest since May 2025 |
| Dollar index | 102.37 | up 0.47% |
| U.S. 10-year yield | 5.262% | below last week’s 24-year high |
| Sterling vs dollar | $1.32064 | down 0.24% |
| Dollar vs yen | 157.92 | yen softer |
| Euro vs Swiss franc | – | euro down 0.4% |
| Euro vs sterling | – | euro down 0.34% |
| French bond futures | – | down 0.13% |
The same board shows why a U.S. jobs miss did not reprice Europe. Treasuries calmed a little. The euro still made the low.
HOW THIS BURST COMPARES WITH 2011
| Measure | 2011 episode | This episode |
|---|---|---|
| Spread widening pace | 104 bp over 106 days | 67 bp in under a month |
| France’s role | Bystander, with German yields falling faster | Frontier, with French yields rising outright |
| French debt load | Near 80% of GDP in 2009 | 119.3% of GDP in 2026 |
| Friday 10-year premium vs Germany | Crisis-era highs that pulled in the ECB | 154 bp, widest since 2011 |
Nordvig’s other warning is political rather than arithmetic. What kept the euro together in 2010-2012 was the will to defend it, not a debt ratio or a bank statistic, and that will is harder to read with big elections stacked ahead.
A Budget Bondholders Do Not Believe
Prime Minister Sébastien Lecornu’s cabinet presented the 2027 budget bills on Thursday, Oct. 1. The official Council of Ministers text puts public debt at 119.3 percent of GDP in 2026, up from 115.7 percent in 2025, and at 121.7 percent in 2027. Interest costs rise from 79.2 billion euros in 2026 to 91.2 billion euros in 2027, a 12.0 billion euro jump that eats more than 0.3 point of GDP on its own.
The deficit target is 5.0 percent of GDP in 2027, against a revised 5.4 percent in 2026. To get there, the finance bill and the social-security bill rest on 43 billion euros of new repair measures. Counting older measures that still ramp up, the total effort reaches €54 billion ($62 billion). Growth is pencilled in at 0.5 percent in 2026 and 1.0 percent in 2027. Lecornu has said that with no savings at all, the 2027 deficit would be around 6.5 percent of GDP.
THE 2027 BUDGET IN FIGURES
- Deficit path: 5.4 percent of GDP in 2026, aiming for 5.0 percent in 2027.
- New versus total: 43 billion euros of fresh measures, 54 billion euros once prior ramps are included.
- Interest bill: 79.2 billion euros in 2026, 91.2 billion euros in 2027.
- Debt ratio: 119.3 percent of GDP this year, 121.7 percent next year.
- Tax line: No general tax rise; the corporate surtax on large firms is cut by a third.
- Reversibility: The cabinet says much of the package can be unwound by the next government.
That last line is catnip for a bond desk. Lecornu told Le Figaro the plan is a political risk and still “a long way from austerity.” He has also said that waiting for the presidential vote before passing a 2027 budget would be choosing disorder, because the debt will not wait. Markets heard the other half of the same sentence: any promise made now is hard to trust with a change of power coming soon.
The Assembly has been hung since Emmanuel Macron’s 2024 snap election. Two previous prime ministers were toppled over austerity, in December 2024 and September 2025. The usual tool is Article 49.3, which lets the cabinet force a budget through without a vote and then survive a no-confidence motion. Parties already lining up for 2027 have less reason to grant that survival. ING has warned that even a 5 percent deficit would be too high to stabilize debt already at 119 percent of GDP. The daily French bond indexes through October 2 still show last week’s selloff in the official series.
Why the Dollar Still Won on Friday
The dollar index rose 0.47 percent to 102.37 on Monday. Sterling slipped 0.24 percent to $1.32064, the yen was at 157.92 per dollar, and the euro also lost 0.4 percent against the Swiss franc and 0.34 percent against sterling. Matthew Ryan, head of market strategy at Ebury, said the dollar is the main winner because higher Treasury yields lift the appeal of U.S. assets while a broad debt selloff feeds haven flows into the greenback.
The French politics trade that many expected would escalate this winter as April 2027 elections neared … is here now.
Brent Donnelly, president of foreign exchange trading, Spectra Markets
Donnelly added that it is not obvious what might fix the move, because budget promises from the current French government are not very credible with a change of power close. OCBC strategists said that if rate volatility stays high, pressure on carry trades, cyclical currencies and the euro is likely to persist, while the Swiss franc and the dollar should stay supported. That is a polite way of saying the jobs miss changed the Fed path at the margin and still left the euro as the funding currency people dump when European fiscal risk wakes up.
Two ECB Hikes Meet a Core-Country Shock
The ECB raised its deposit rate to 2.50 percent on Sept. 10, the second increase this year, and lifted the main refinancing rate to 2.65 percent. Christine Lagarde, the ECB president, refused to pre-commit to the Oct. 29 meeting and has described policy as data-dependent and measured, pointing to tighter financial conditions from higher long-term yields. An October hike was already a stretch. A French spread at 2011 levels makes a December one harder too, because more tightening would land on the very sovereign the market is marking down.
Lagarde has treated the global bond selloff as a worldwide move, not a euro-only accident. That stance fits a bank whose job is inflation, not a particular Franco-German gap. Energy prices and the Middle East war have kept euro-area inflation above the 2 percent target, which is why a bond-buying backstop is a much heavier lift than it was when Mario Draghi could say “whatever it takes” into falling inflation. If the ECB did buy OATs to cap the spread, traders would read that as less room to hike, which would be another euro-negative.
France is also still under the EU’s excessive deficit procedure, opened in July 2024. That makes it harder to argue that the stress is “unwarranted,” the usual test for emergency tools. Moody’s Ratings, which has France at Aa3 with a negative outlook, reviews the credit on Oct. 23 and has already said political fragmentation is the issue it is watching.
April 2027 Is Already in the Price
The presidential vote is set for April 18 to May 2, 2027, and Marine Le Pen remains ahead in polling against a splintered center and left. Assembly debate on the budget is due to start on Tuesday, Oct. 13, with a target vote on Nov. 17. If no bill passes by year-end and 49.3 is not used, Paris can roll last year’s budget forward on a special law, which would leave a full 2027 budget until well into the second half of the year, after a new president and, likely, a new parliament.
THE CALENDAR MARKETS ARE TRADING
- September 10, 2026: The ECB lifts the deposit rate to 2.50 percent and Lagarde declines to lock in the next move.
- September 18, 2026: The 10-year French-German spread crosses 100 basis points for the first time since 2012.
- October 1, 2026: Lecornu’s cabinet presents the 2027 bills; the 10-year OAT yield hits 4.96 percent.
- October 2, 2026: The spread reaches 154 basis points; U.S. payrolls print 29,000.
- October 5, 2026: The euro trades down to $1.1161, the weakest since May 2025.
- October 13, 2026: National Assembly debate on the budget is due to open.
- October 23, 2026: Moody’s is scheduled to review France’s Aa3 rating.
- November 17, 2026: The government has a target date for a budget vote.
- April 18-May 2, 2027: France holds its presidential election.
French political talk over the weekend had already jumped past the budget arithmetic. The live argument is that next spring’s vote is the crisis, not the clean-up, because whoever wins inherits 121.7 percent debt, a hung parliament, and a coupon that is compounding faster than 1 percent growth. Donnelly’s winter trade did not wait for winter. The euro’s 17-month low is what that looks like in the spot market, on a Monday when U.S. jobs had just given the dollar a reason to rest.
Moody’s Oct. 23 review and the Nov. 17 vote are the next numbered tests. Until one of them changes the fiscal story, the euro is trading French politics six months early, and the dollar is collecting the bid that a 29,000-job print was supposed to weaken.
Disclaimer: This article is news reporting and market analysis for information only. It is not investment advice, a recommendation to buy or sell the euro, Treasuries, French OATs, or any other security, and it is not a forecast you should trade on. Speak with a licensed financial adviser or portfolio manager who knows your situation before making any currency or bond decision. Levels, ratings, and political dates reflect the official releases and market prints cited here as of Oct. 5, 2026, and can move without notice.

Ohtani Game 4 Logoman Card Sells for $3.24 Million

Cole Kmet’s Season Ends, and Chicago’s Tight End Plan Starts

NBA Seeks Soccer Money After EuroLeague Clubs Refused

Amazon’s First Bond Tests Leave the Broccoli Chair Empty

Tyrese Maxey Owns the Night Built for LeBron James

Warsh Rejects Rate Guidance and Still Moves Markets

Dana-Farber Exits an MGB Medicare Advantage Network Early

NASA Launches the Roman Space Telescope’s Cosmic Bet

OpenAI’s Cyber Letter Puts the Defense Bill on Governments

Russia Recycles Its Old Warning Over Storm Shadow Plants
-
 BUSINESS2 months ago
Warsh Rejects Rate Guidance and Still Moves Markets
-
 BUSINESS1 month ago
Dana-Farber Exits an MGB Medicare Advantage Network Early
-
 NEWS2 months ago
NASA Launches the Roman Space Telescope’s Cosmic Bet
-
 NEWS2 months ago
OpenAI’s Cyber Letter Puts the Defense Bill on Governments
-
 NEWS2 months ago
Russia Recycles Its Old Warning Over Storm Shadow Plants
-
 ENTERTAINMENT4 weeks ago
Primetime’s $2.7 Million Preview Tops Pitt’s Costlier Film
-
 BUSINESS2 months ago
Jet Drones Lock Down Kyiv and Strip Kherson of Heat
-
 NEWS2 months ago
Congo Starts Ervebo Vaccinations for a Different Ebola Virus