NEWS
Hotel Chains Keep Building as the Gulf Peak Stalls
Hotel chains still feed a record Gulf pipeline as Accor budgets a 12% fourth-quarter RevPAR drop and Riyadh demand slides.

The world’s largest hotel groups are still feeding a record Gulf building boom even as they guide the region’s peak season to a fresh drop in room revenue. Accor, the most exposed, is budgeting a 12% decline in Middle East revenue per available room, or RevPAR, for the fourth quarter after a 3% drop in the third.
That split is the wager. The Middle East is about 11% of Accor’s global room revenue and only about 3% of Marriott’s open rooms, yet it is a much larger share of the rooms these companies still intend to open. Lodging Econometrics closed the third quarter with a regional construction record, and the brands keep signing.
The Q3 Rebound Hit the Off-Season
The U.S.-Iran war began on February 28 and gutted second-quarter trading. Marriott’s Middle East RevPAR fell more than 40%. IHG’s wider Middle East book was down 19%. Accor called the second quarter severely disrupted and turned on a profit-protection plan in March.
July through September looked like a bounce because it is not when the Gulf prints its year. Accor’s Middle East RevPAR was down only 3%. Group CFO Martine Gerow told the October 22 call that Saudi Arabia and Egypt continued to perform well and that the UAE improved a lot from the second quarter, with RevPAR still down around 20% and occupancy back in the mid-60s. Accor’s global RevPAR rose 4.9%, or 5.6% with the Middle East taken out, and Q3 revenue reached €1,503 million, up 7.7% at constant currency.
The company still upgraded its full-year EBITDA range to €1,270 million to €1,285 million. Gerow said the fourth-quarter RevPAR guide assumes no material change in UAE trading versus the third quarter and a tougher view on the rest of the region. “With respect to the RevPAR, for the Middle East overall, we are actually assuming roughly minus 12%, which is worse than what we have seen in the third quarter, because the third quarter was minus 3%,” she said.
Peers told the same story in different words. Marriott improved to a 12% Middle East RevPAR decline. Hilton’s Middle East and Africa RevPAR fell 5.6%. IHG was broadly flat across the wider region and down 12% across the six Gulf countries. Hyatt held the drop to about 3% because domestic trips offset a 40% fall in international inbound. Wyndham improved to down 13% after a 45% second-quarter slide. The recovery sat in the shoulder. The money quarter was still ahead, and it is the one they now dislike.
Peak Season Lost Its Flights and Its Calendar
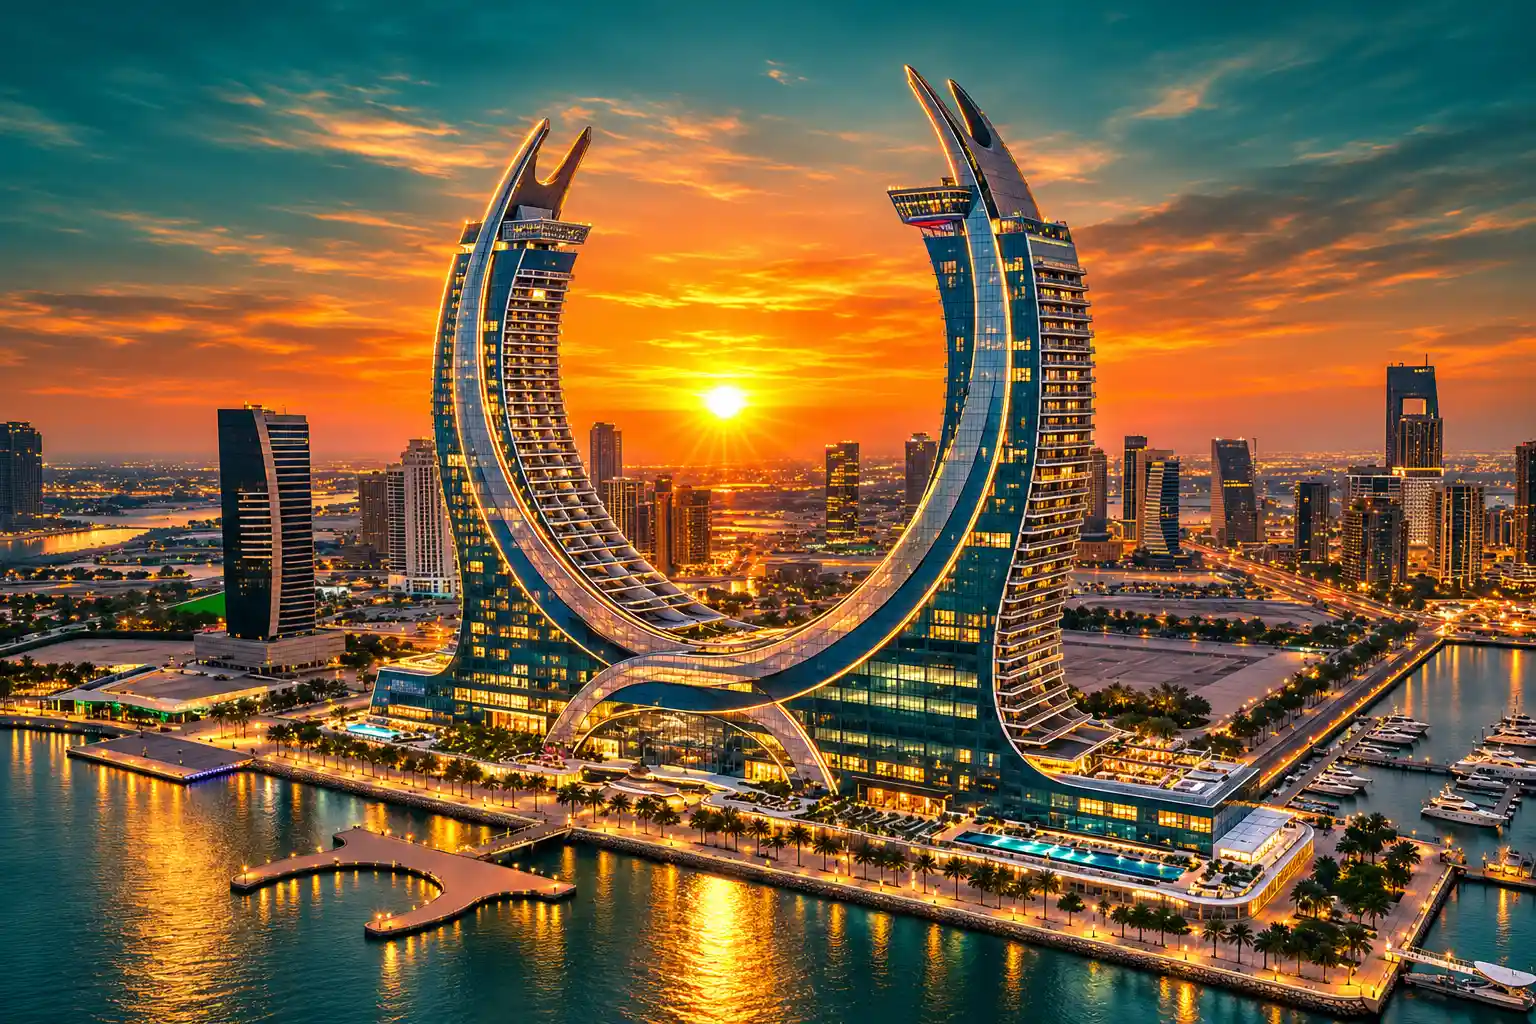
October is when Gulf hotels usually raise rates on events, holidays and winter sun. This October, Yemen’s Houthis hit Saudi airports, ports and oil sites. Cirium, the aviation data firm, counted 4,071 cancellations out of 4,736 scheduled flights at Riyadh’s King Khalid International Airport from October 8 through October 25, about 86%. Across Saudi airports it counted more than 7,800 cancelled departures, 45% of the schedule, with the worst day on October 12, when cancellations passed 60% nationwide.
THE OCTOBER FLIGHT HOLE
- Riyadh airport: Cirium logged about 86% of King Khalid flights cancelled from October 8 through October 25, or 4,071 of 4,736 scheduled.
- Nationwide: More than 7,800 Saudi departures were cancelled in that window, 45% of the schedule.
- The peak day: Cancellations exceeded 60% of scheduled flights across the kingdom on October 12.
- The warning: On November 7 the U.S. Virtual Embassy in Iran warned Americans of Houthi attacks on Saudi airports and of further flight cancellations.
Large gatherings left with the aircraft. Organisers postponed the Future Investment Initiative, planned for October 26 to 29, to 2027. An EU-Gulf leaders’ meeting set for October 24 was put off. The Six Kings Slam tennis exhibition moved. Marriott finance chief Jen Mason told analysts the company now projects “a more meaningful year-over-year RevPAR decline in the Middle East in the fourth quarter than in the third,” pointing to tough comparisons with late 2025, when big events lifted average rates, and to fresh Saudi cancellations. She also noted that because the peak tourism season begins in October, a decline hits Europe-Middle East-Africa results harder than it did in the third quarter.
FROM THE FEBRUARY WAR TO THE PEAK-SEASON GUIDE
- February 28, 2026: The U.S.-Iran war begins and second-quarter Gulf hotel demand collapses.
- March 2026: Accor activates a profit-protection plan to offset the trading hit.
- July to September 2026: RevPAR recovers from the second-quarter trough as local and regional demand returns.
- October 8, 2026: Houthi strikes on Riyadh’s airport empty the peak-season inbound flow.
- October 19, 2026: The Future Investment Initiative is postponed to 2027; other Riyadh fixtures slip.
- October 21, 2026: Riyadh Season still opens, a local entertainment calendar running without the usual foreign crowd.
- October 22 to November 2, 2026: Accor, Hilton, IHG, Hyatt and Marriott guide the fourth quarter weaker than the third.
By November 12 the airport was handling limited domestic and international flights, and many foreign airlines were still staying away. The rooms that should have been full of conference guests were not.
Accor Has 11% of Room Revenue in the Region
Exposure is not even, which is why Accor’s 12% fourth-quarter assumption matters more than Marriott’s steeper decline on a smaller base. Accor takes about 11% of global room revenue from the Middle East, with Saudi Arabia around 5% and the UAE around 4%. IHG puts the region at roughly 5% of its business. Marriott said the Middle East is about 3% of open rooms and about 3% of global gross fees last year. Hilton’s Middle East and Africa set is 176 hotels and 43,579 rooms.
Q3 RESULTS AND THE LATER GUIDE
| Group | Q3 Middle East RevPAR | What they now assume | Weight in the business |
|---|---|---|---|
| Accor | Down 3% | About 12% down in Q4 | About 11% of global room revenue |
| Marriott | Down 12% | A steeper Q4 drop than Q3 | About 3% of open rooms |
| Hilton | Down 5.6% in MEA | Low double-digit MEA drop for the full year | 176 hotels, 43,579 rooms in MEA |
| IHG | Region flat; six GCC states down 12% | No separate Q4 Gulf figure given | About 5% of the business |
| Hyatt | Down about 3% | Q4 weaker than Q3 | About $10 million less in full-year fees |
Gerow said incentive fees, the extra payments tied to hotel profits, still lagged in the third quarter even as occupancy in the UAE climbed back into the mid-60s. Accor’s group occupancy was 71%. Hilton’s Middle East and Africa occupancy fell 5.0 points to 64.8%. Those are different networks, but they rhyme: rooms are selling again, not at peak-season prices, and not to the visitors who used to fly in for four-day forums.
IHG chief executive Elie Maalouf said growth in Europe and East Asia more than offset “a broadly flat performance in the Middle East.” Egypt and Turkey ran well ahead, which is the same split Accor reported. The pain is concentrated in the six GCC states, not in the whole map labelled Middle East on an earnings slide.
A Record 771 Projects Went Into the Pipeline
Development did not wait for the inbound flights to return. Lodging Econometrics closed the third quarter with a record 771 hotel projects in the pipeline and 188,960 rooms, up 17% by projects and 15% by rooms from a year earlier. At the end of the second quarter the same tracker had 724 projects and 178,003 rooms, so the book added 47 projects and 10,957 rooms during a quarter when chains were still reporting war damage.
Of that total, 329 projects and 82,594 rooms were already under construction, 43% of projects and 44% of rooms. Another 184 projects and 53,675 rooms were scheduled to start within 12 months. Luxury and upscale together accounted for 410 projects and 102,457 rooms, 53% of projects and 54% of rooms. The region opened 36 hotels and 6,319 rooms in the first three quarters. Lodging Econometrics forecasts 28 more hotels and 4,091 rooms in the fourth quarter, for 64 hotels and 10,410 rooms on the year.
WHERE THE NEW ROOMS ARE PLANNED
| Market | Projects | Rooms | Share of regional rooms |
|---|---|---|---|
| Saudi Arabia | 401 | 109,320 | 58% |
| Egypt | 192 | 40,661 | – |
| United Arab Emirates | 111 | 26,800 | – |
| Riyadh (city) | 114 | 23,049 | – |
| Makkah (city) | 34 | 22,109 | – |
| Dubai (city) | 65 | 15,067 | – |
Saudi Arabia is 52% of regional projects and 58% of rooms, up 15% and 16% year over year. Egypt is the fast grower, up 47% in projects and 42% in rooms to 192 projects and 40,661 rooms. Oman has 27 projects and 4,618 rooms. Iraq has 10 projects and 2,331 rooms. Riyadh leads cities with 114 projects and 23,049 rooms. Cairo has 71 and 14,663. Jeddah has a record 63 projects and 14,384 rooms.
The brands’ own books match the tracker. Accor ended September with more than 273,000 rooms in a 1,628-hotel pipeline, up 9.5%, against a live network of 885,219 rooms in 5,857 hotels. It opened 63 hotels and nearly 9,000 rooms in the third quarter. Marriott’s global pipeline passed 634,000 rooms across 4,209 properties, with more than 278,000 rooms under construction. Hilton’s pipeline is 543,100 rooms; it opened 182 hotels and 27,000 rooms in the quarter, a 6.0% net unit rise, and logged more than 20 Middle East and Africa signings. IHG’s pipeline is 353,000 rooms across 2,426 hotels. It signed 164 hotels in the quarter, opened 92, and said it knew of no project cancellations. Hyatt’s executed pipeline reached about 158,000 rooms, up 12.1%. Wyndham signed five new contracts in Saudi Arabia and the UAE.
Accor did trim net unit growth to 3.0% to 3.5% from around 3.5%, citing China midscale closures and a chance of delayed fourth-quarter openings. That is a timing hedge, not a freeze. The steel already in the ground is the tell.
The $20 Million Drag on Hilton’s Owned Hotels
Fee-based chains can wait. Owners of standing hotels cannot. Hilton still owns a slice of its system, and that is where the war shows up in cash. Through nine months, Middle East and Africa RevPAR was down 12.3%. Hilton now expects a low double-digit decline for the full year in that region, and it cut full-year adjusted EBITDA guidance to $4,060 million to $4,080 million, citing weaker Middle East trading and softer timeshare license fees.
I think The Middle East will be a heck of a lot better next year than this year. I mean, that is my view. Ownership will take a couple of years, but the reality is ownership’s probably in and of itself $20 million-plus drag this year.
Christopher J. Nassetta, president and CEO, Hilton Q3 earnings call
Hyatt’s hit is smaller and cleaner because it is mostly fees. Joan Bottarini said on the company’s call that Middle East RevPAR fell only 3% in the third quarter as domestic travel offset a 40% drop in international inbound, and that Hyatt still expects a $10 million impact to annual fees, with the fourth quarter below the third because of seasonality and the war. Accor said slower incentive-fee growth in the Middle East weighed on both its Premium, Midscale and Economy management-and-franchise line and its Luxury and Lifestyle line. The brands still collected base fees. The profit kicker did not.
That is why signings can rise while earnings in the region fall. A management contract on a hotel that will open in 2028 does not care that Riyadh’s airport cancelled 86% of its flights in mid-October. The owner of a tower that opened in 2024 does.
Riyadh Fell 24.8% While Makkah Kept Growing
The kingdom is not one market. JLL’s third-quarter Saudi hospitality note put nationwide RevPAR at SAR 413.1 year to date through September, with occupancy down 1.6 points to 58.6%. Riyadh RevPAR was down 24.8%. Jeddah slipped 1.3%. Makkah, the religious market, was up 7.8%. Madinah held occupancy at 71.9% with RevPAR down 0.9%.
SAUDI HOTELS, CITY BY CITY
- Riyadh: RevPAR down 24.8%, the steepest fall JLL recorded, in the city with 114 pipeline projects.
- Jeddah: RevPAR down 1.3%, with a record 63 projects still on the board.
- Makkah: RevPAR up 7.8%, on 34 projects and 22,109 rooms, almost as much capacity as Riyadh on far fewer sites.
- New money: The Hospitality Investment Enablers Program listed 19 projects across five destinations, aiming for SAR 6.7 billion and more than 3,000 keys.
Pilgrimage demand does not need a clear inbound long-haul schedule the way a Davos-style forum does. Corporate Riyadh does. The pipeline still treats Riyadh as the prize, with 23,049 rooms planned against 22,109 in Makkah. Chains are adding the most rooms in the city whose peak-season machine just broke, on the view that Expo 2030 and a later World Cup will refill them. JLL itself still calls the medium-term outlook positive and says capital will get choosier, which is a polite way of saying some of those 114 Riyadh projects will slip.
Marriott’s 2027 Recovery Is the Working Bet
Anthony Capuano, Marriott’s chief executive, called conditions “highly volatile” on the November 2 call and said the company is “currently assuming ongoing travel disruption with some gradual improvement during the course of 2027.” Easier comparisons, he said, arrive after the first quarter. Mason has already told investors the fourth quarter will look worse than the third. That is a 15-month clock, not a winter blip.
I was in Dubai for a few days last week. I had dinner with 65 of our UAE general managers, who expressed an enormous amount of confidence in the steepness of the recovery curve when they get a sense in the region that there is some stability or resolution to the conflict.
Anthony Capuano, CEO, Marriott Q3 earnings call
Accor is not waiting for that dinner to fill rooms. From November 9 through December 31 it is giving Classic and Silver members 20% more value on award stays at participating hotels in the Gulf and nearby markets, so 1,000 points offset €24 instead of €20. Gold and higher tiers are left out. The cheap award inventory is the first thing a chain puts on sale when cash demand is thin, and it is a different tool from cancelling a concrete pour.
WHAT THE Q4 CALENDAR NO LONGER HOLDS
- The investment forum: The Future Investment Initiative, set for October 26 to 29 in Riyadh, was postponed to 2027.
- The diplomatic meeting: An EU-Gulf leaders’ summit planned for October 24 was postponed.
- The tennis draw: The Six Kings Slam exhibition was pushed later, with organisers citing organisational and logistical challenges.
- The local season: Riyadh Season still opened on October 21, a domestic crowd where the foreign one did not land.
Nassetta thinks next year will be a lot better and that owned hotels need a couple of years. Capuano’s general managers in Dubai are waiting for a sense of stability. Gerow has already taken a tougher view on this fourth quarter and still raised group EBITDA because the rest of the world paid the bill. The record 771-project book is what those views are financing. The empty peak is what the owners of the rooms already open are financing now.
Capuano’s 65 general managers ate dinner in a city whose RevPAR was still down around 20% at Accor and talked about the steepness of the curve once someone calls the war finished. The construction cranes in Riyadh, 114 projects deep after a 24.8% RevPAR fall, are the same argument in steel.

Ken Urker’s Accidental Overdose Leaves His Finders Waiting

A Third Carrier Arrives as Hormuz Tankers Keep Burning

Shoe Prices Hit a Record as Flagship Pairs Stay Put

Nvidia’s First Call Without Huang Tests the Money Machine

Blake Griffin Says Oklahoma City Taxpayers Bought a Thunder Arena

Warsh Rejects Rate Guidance and Still Moves Markets

Davina McCall Reveals Cardiovascular Disease After Cholesterol Warnings

Dana-Farber Exits an MGB Medicare Advantage Network Early

NASA Launches the Roman Space Telescope’s Cosmic Bet

OpenAI’s Cyber Letter Puts the Defense Bill on Governments
-
 BUSINESS3 months ago
Warsh Rejects Rate Guidance and Still Moves Markets
-
 ENTERTAINMENT4 weeks ago
Davina McCall Reveals Cardiovascular Disease After Cholesterol Warnings
-
 BUSINESS2 months ago
Dana-Farber Exits an MGB Medicare Advantage Network Early
-
 NEWS3 months ago
NASA Launches the Roman Space Telescope’s Cosmic Bet
-
 NEWS3 months ago
OpenAI’s Cyber Letter Puts the Defense Bill on Governments
-
 NEWS3 months ago
Russia Recycles Its Old Warning Over Storm Shadow Plants
-
 ENTERTAINMENT2 months ago
Primetime’s $2.7 Million Preview Tops Pitt’s Costlier Film
-
 BUSINESS3 months ago
Jet Drones Lock Down Kyiv and Strip Kherson of Heat